Knowledge Center
Catastrophic health plans can help protect you from major medical costs. Learn what to expect before choosing this type of coverage.
What are catastrophic health plans?
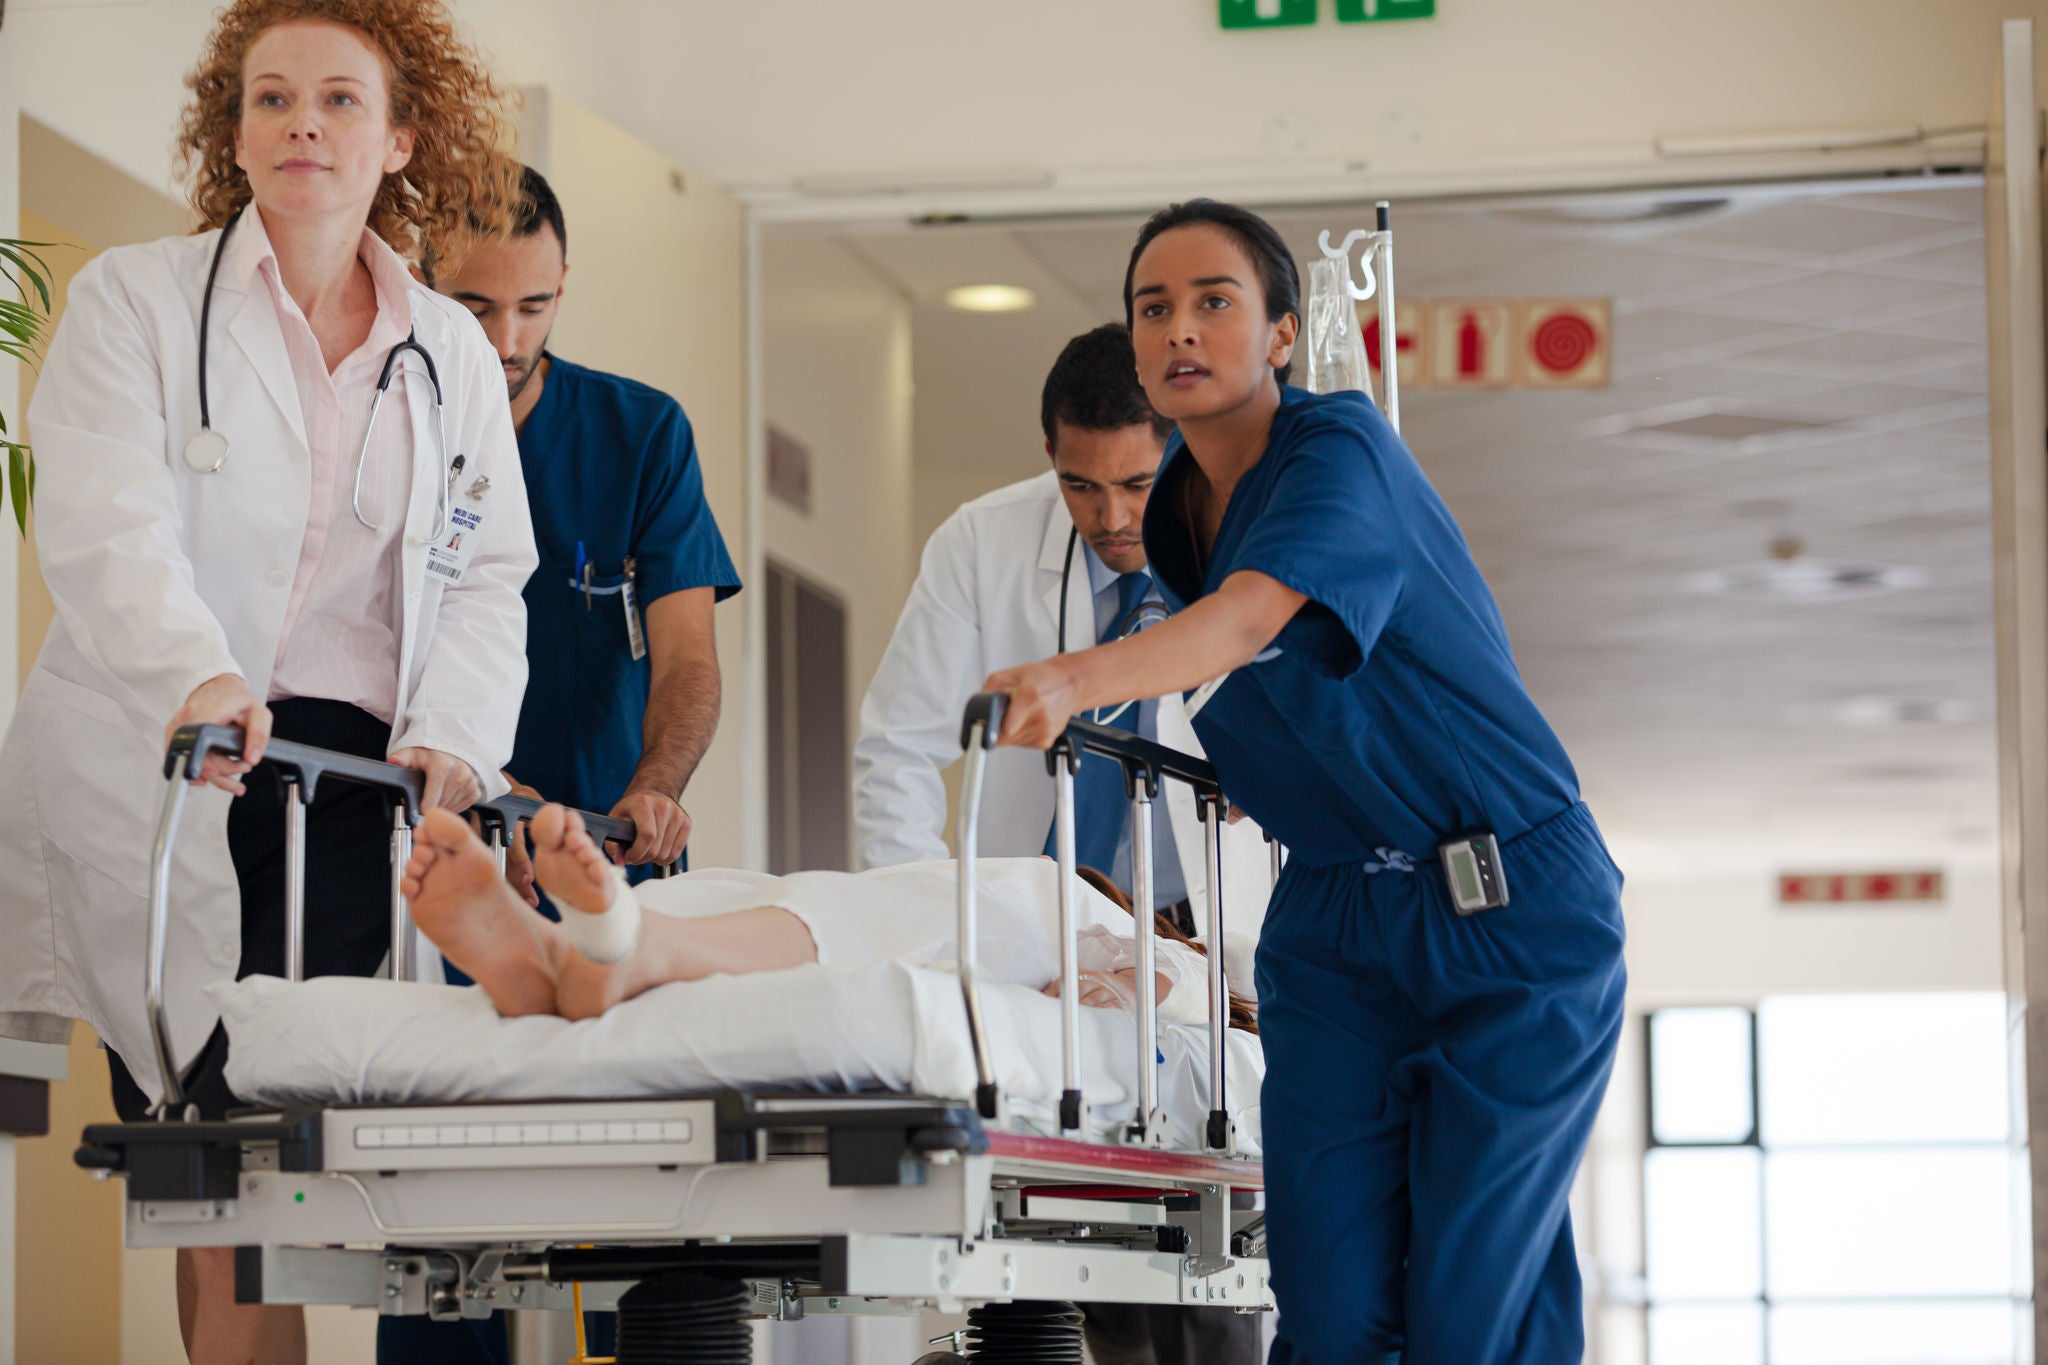
Catastrophic health plans are low-premium, high-deductible insurance plans that are designed to help cover large medical bills in situations like serious injuries or unexpected illnesses.
The low premium means you'll have a lower monthly bill, but because these plans have high deductibles, you’ll pay more of your medical care out-of-pocket before your insurance starts to pay.
So you'll pay the full bill for routine care, medications, and things like visits to specialists, emergency room visits, and hospital stays until you meet your deductible, which can be thousands of dollars for a catastrophic plan. That's why these plans are best suited for protection against a worst-case scenario, rather than everyday health care expenses.
lh-rounded
true
lh-circular
false
lh-full-width
false
How catastrophic health plans work
These plans work a little differently than other Affordable Care Act (ACA) plans, trading lower monthly premiums for higher out-of-pocket costs when you need care. Here's a closer look at what you can expect.
layout
vertical-left
theme
primary-light
media-type
none
icon-size
xxl
gradient
false
bg-fill
false
eyebrow-size
md
title
Low premiums, high deductible
heading-level
h3
heading-size
xxs
title-alt
true
rte-description
The monthly payments are the lowest of any ACA plan, but you’ll pay the full price of your medical care until you hit your deductible.
cta1-variant
text
cta2-variant
text
layout
vertical-left
theme
primary-light
media-type
none
icon-size
xxl
gradient
false
bg-fill
false
eyebrow-size
md
title
Preventive care is still free
heading-level
h3
heading-size
xxs
title-alt
true
rte-description
Even if you haven’t met your deductible yet, you get three primary care visits and coverage for preventive care services, like screenings and vaccines, at no cost.[D]
cta1-variant
text
cta2-variant
text
layout
vertical-left
theme
primary-light
media-type
none
icon-size
xxl
gradient
false
bg-fill
false
eyebrow-size
md
title
No premium subsidies
heading-level
h3
heading-size
xxs
title-alt
true
rte-description
Some ACA plans can get subsidies that help lower your costs, but catastrophic health plans aren’t eligible.[D]
cta1-variant
text
cta2-variant
text
layout
vertical-left
theme
primary-light
media-type
none
icon-size
xxl
gradient
false
bg-fill
false
eyebrow-size
md
title
Enroll through the Health Insurance Marketplace®
heading-level
h3
heading-size
xxs
title-alt
true
rte-description
You can only enroll in a catastrophic health plan during the open enrollment period every fall or during a Special Enrollment Period (SEP) if you have a qualifying life event.[D]
cta1-variant
text
cta2-variant
text
rendition
standard
lh-rounded
true
lh-circular
false
lh-full-width
false
Who can get a catastrophic health plan
Not everyone can buy a catastrophic health plan. Generally, you must be under 30 years old to enroll in one.
If you're 30 or older, you'll need to apply for a hardship exemption or an affordability exemption to buy a catastrophic health plan.[D] You might get a hardship exemption if you experience difficult life events that prevent you from getting standard health insurance, like facing eviction, filing for bankruptcy, or suffering from a natural disaster.
An affordability exemption applies if the lowest-priced standard health care options cost more than a certain percentage of your total household income. If standard plans are too expensive based on what you earn, you can apply for this exemption.
Is a catastrophic plan right for you?
The right answer depends entirely on your budget and your daily health needs.
If you are young, highly active, and rarely visit the doctor, a catastrophic plan may save you money on monthly premiums. The plan would be protection against the costs of a worst-case health event. But if you need regular checkups, take medications, or see specialists often, the high deductible might cost you much more over the year.
Also keep in mind that catastrophic plans don't qualify for premium subsidies.[D] If your income qualifies you for a tax credit, a Bronze or Silver tier plan might end up being cheaper than a catastrophic plan.
Take a close look at your personal health history, your current income, and your savings. Think about whether you could comfortably afford to pay a high deductible if a major medical emergency happens tomorrow.
Take the confusion out of insurance
Get reliable answers to your insurance questions, such as how to get prior authorization or submit a claim.
layout
vertical-left
theme
white
media-type
image

icon-size
xxl
gradient
false
bg-fill
false
eyebrow-size
md
title
Finding the right health insurance plan for you
heading-level
h3
heading-size
xs
cta1-variant
text
cta1-text
Read more
cta1-srtext
Read more about finding the right plan for you
cta2-variant
text
layout
vertical-left
theme
white
media-type
image

icon-size
xxl
gradient
false
bg-fill
false
eyebrow-size
md
title
Health insurance options for young adults
heading-level
h3
heading-size
xs
cta1-variant
text
cta1-text
Read more
cta1-srtext
Read more about insurance options for young adults
cta2-variant
text
layout
vertical-left
theme
white
media-type
image

icon-size
xxl
gradient
false
bg-fill
false
eyebrow-size
md
title
What the Affordable Care Act means for you
heading-level
h3
heading-size
xs
cta1-variant
text
cta1-text
Read more
cta1-srtext
Read more about the Affordable Care Act
cta2-variant
text